Saudi Pipeline Outage Threatens 4% Hit to Global Oil Supplies
A prolonged shutdown of the East-West pipeline could test Saudi export resilience and sharpen pressure on oil markets already strained by regional conflict.
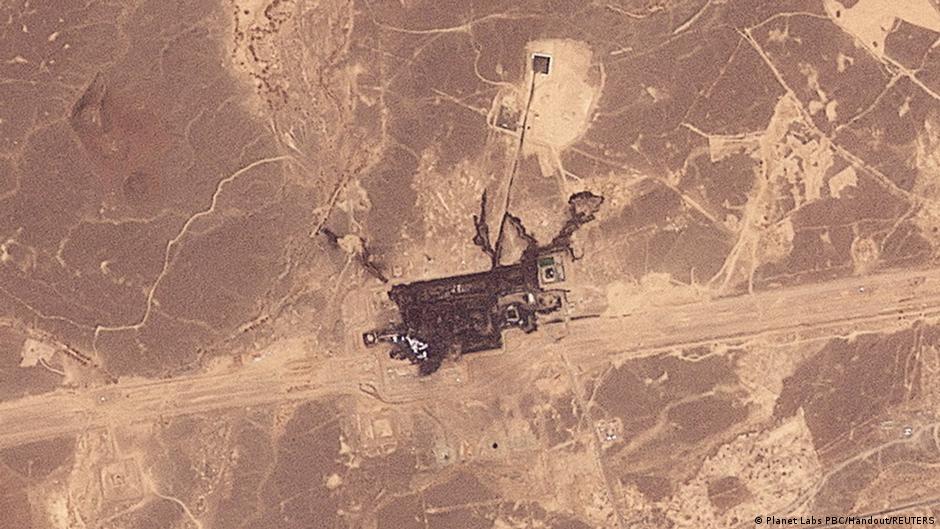
A prolonged halt on Saudi Arabia’s East-West oil pipeline could reduce global oil supplies by 4 percent if Riyadh is unable to restore operations in the coming days, according to Reuters, citing informed sources in the oil market. The uncertainty over the duration of repairs has turned what Saudi authorities initially described as a precautionary shutdown into a potentially significant stress point for global energy markets.
The pipeline was stopped on September 11 after drone attacks from Iraqi territory targeted the provinces of Riyadh and Medina. Saudi Arabia’s energy ministry said the suspension was taken as a “precautionary measure,” but officials have not provided full information about the scale of the damage or the timing of a restart. For oil consumers, traders and policymakers, that lack of clarity is itself economically important: the market is being asked to price a major infrastructure disruption without a reliable repair schedule.
The East-West pipeline is one of Saudi Arabia’s most strategically important export routes. Stretching 1,200 kilometers, it links the country’s main oil fields in the east with the Red Sea port of Yanbu. Its role has become more central because it allows Riyadh to ship millions of barrels of oil per day without using the Strait of Hormuz, where traffic has been restricted by Iran.
One Reuters source said repairs could take five to six weeks, while another said work could be completed more quickly and pumping might resume before all repairs are finished.
That range of possible outcomes matters well beyond Saudi Arabia. A shutdown lasting several days may be absorbed through inventories and rerouting. A disruption measured in weeks would be a different macroeconomic event, especially if it limits the kingdom’s ability to maintain export volumes at a time when geopolitical risk is already embedded in the price of crude.
A Strategic Route Under Pressure
Saudi Arabia significantly increased its use of the East-West pipeline after the start of the war against Iran. By June, oil exports through the route had reached nearly 8 million barrels per day, according to estimates by the International Energy Agency. That scale underscores why the pipeline is not merely a national asset but a key part of the global oil supply system.
The pipeline’s economic function is straightforward: it gives Saudi Arabia flexibility. When Hormuz becomes less reliable or more politically constrained, the Red Sea route through Yanbu offers an alternative path to market. In periods of heightened regional confrontation, that flexibility can help stabilize export flows and reassure importers. If the pipeline is impaired, the market loses part of that buffer.
In recent weeks, however, the route’s throughput had already been reduced by attacks by the Houthis on Saudi tankers in the Red Sea. In August, about 2.5 million barrels per day were shipped through Yanbu, the lowest level since 2013, according to the IEA’s latest monthly report. The pipeline outage therefore comes after a period of declining use, not from a position of full operational normality.
For senior decision-makers, the immediate question is whether Saudi Arabia can prevent a logistical disruption from becoming a supply shock. The sources cited by Reuters warned that if the pipeline is not restored in the coming days, Saudi Arabia could face a shortage of oil stocks available for export. Their assessment points to a possible 4 percent decline in global supplies, a figure large enough to affect inflation assumptions, refinery planning and fiscal calculations in both producing and consuming economies.
Policy and Market Consequences
The implications extend across several policy domains. For central banks, a renewed rise in oil prices would complicate inflation management, particularly if the shock is viewed as persistent rather than temporary. For finance ministries, higher energy prices can widen subsidy burdens in import-dependent economies and alter revenue expectations in oil-exporting states. For corporate planners, the disruption adds another variable to procurement, shipping and hedging decisions.
The uncertainty also highlights the growing vulnerability of energy infrastructure to drone warfare and attacks on maritime logistics. Saudi Aramco was able to bring the East-West pipeline back into service quickly after an attack in April. The current incident is being watched closely because a slower recovery would suggest either more substantial damage or a more difficult operating environment. Neither interpretation would be comforting for markets.
The Red Sea dimension is particularly important. If attacks on tankers continue to constrain the use of Yanbu while the pipeline itself remains offline or partially impaired, Saudi Arabia’s ability to bypass Hormuz is weakened at both ends of the export chain. That could increase the strategic premium attached to Middle Eastern crude flows and raise the cost of disruption insurance for consumers and shippers.
For now, the key facts remain limited but consequential. The pipeline has been shut since September 11. Saudi authorities have not disclosed the full extent of damage or a clear timeline for resumed pumping. Market sources differ on whether repairs could take five to six weeks or be accelerated, with oil flows resuming before the completion of all work. The potential loss, if the disruption persists, is estimated at 4 percent of global supply.
The broader economic message is that spare logistics capacity has become as important as spare production capacity. Saudi Arabia may still have oil in the ground and production capability, but the ability to move barrels to export markets is now the binding constraint under scrutiny. In a fragmented geopolitical environment, pipelines, ports and sea lanes are increasingly part of the macroeconomic transmission mechanism.
Until Riyadh provides greater clarity, oil markets will have to weigh the risk of a short operational pause against the possibility of a prolonged constraint on one of the world’s most important export corridors. That uncertainty alone may influence prices, inventories and policy calculations in the days ahead.